2026 Mid-Year Outlook for the Pneumatic Industry
I. Industry overview: Growth Shifting Gears, Structural Divergence
In the first half of 2026, China's pneumatic industry saw slower growth but improved structure. Market size was approximately Rmb 32.55 billion in 2024 and RMB68 billion in 2025,with an 11.5% CAGR. Q1 2026 output and sales grew 15.2% year-oon-year, but full-year growth is expectes to fall to 5%--8%. Growth drivers are shifting from traditional general machinery to new energy vehicles, electronics, and emiconducyors. The industry is transitioning from "scale-driven" to "structure-driven."
II. Competitive Landscape: Domestic Substitution Accelerating
SMC, AirTAC, and Festo remain the top three, with a combined 63% share. AirTAC is growing against the trend thanks to localization cost advantages. Foreign brands still hold nearly 70% of the high-end market, but in mid-to-low-end standardized products, domestic substitution is irreversible. Government procurement requires over 50% domestic high-end equipment, with local tax incentives for supporting manufacturers. Competition is shifting from "can we make it" to "can we make it well."
III. Technology Trends: Intelligence and Green Manufacturing as Hard Constraints
Intelligence has moved from a bonus to an entry ticket. The global smart pneumatics market is expected to reach USD 5.16 billion in 2026, with sensing and communication-enabled components becoming standard. On green manufacturing, low-power solenoid valves and high-efficiency pneumatic motors are favored, while high-energy-consumption products face elimination. Product definition is changing: not just thrust and life, but system connectivity, monitorability, and energy consumption.
IV. Key Segments: Three Accelerating Directions
-
New energy vehicle production lines: Demand for high-precision pneumatic components from three-electric systems is surging, with domestic localization at 55%.
-
Electronics and semiconductors: Equipment localization drives demand for precision pneumatic components, with extreme requirements for accuracy and cleanliness.
-
Logistics automation: Miniature solenoid valve shipments exceeded 80 million units, with continued demand from express sorting and warehouse automation.
These segments share high performance requirements, strong customer stickiness, and low price sensitivity—ideal for companies with technical depth.
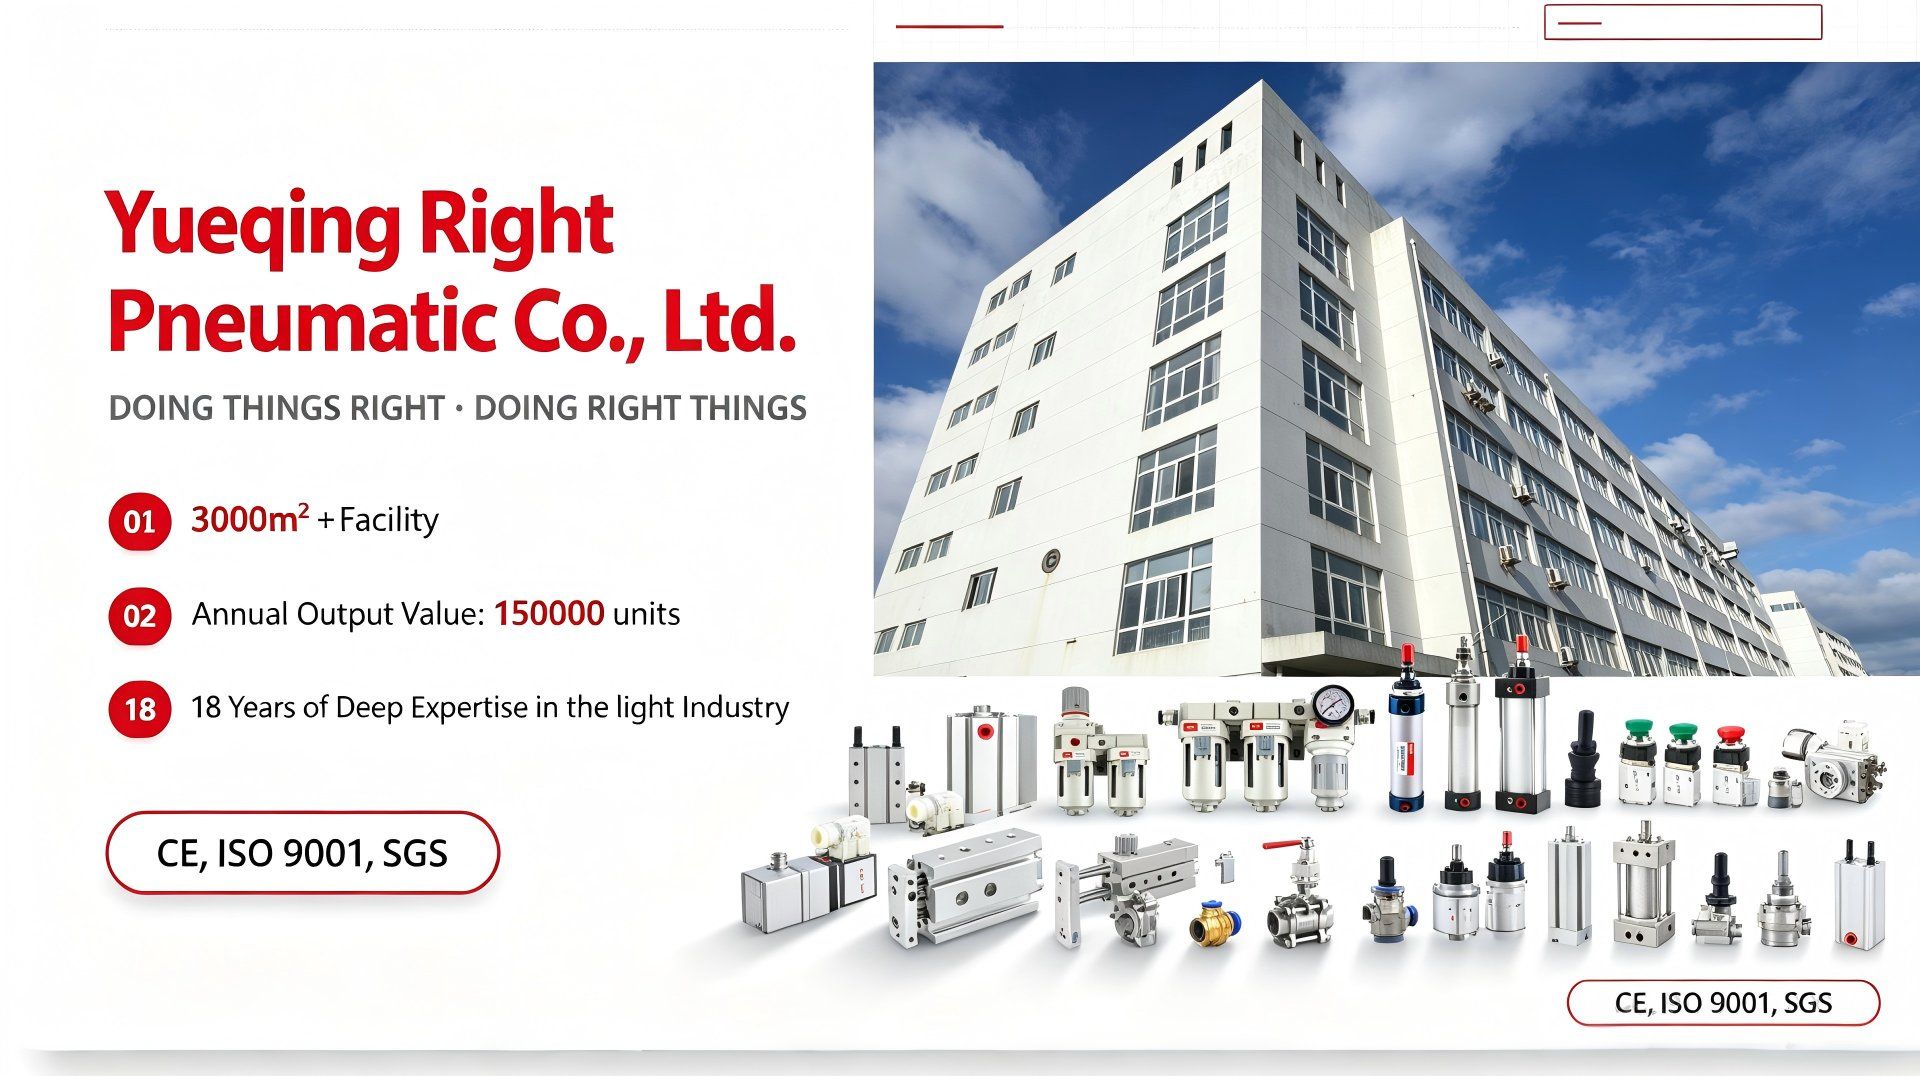
V.Ruiheng Pneumatics: Solid Manufacturing, Reliable Service
At a time when the industry is shifting toward structural upgrading, Ruiheng Pneumatic (RIH) has a clear positioning: not the cheapest, but the mmost solid.
Products: Ruiheng focuses on durable standard cylinders. The SU series standard cylinders have barrels and end caps more than twice the thickness of competitors, with bidirectional YCC seals. The SRC series 90-degree rotary clamp cylinders feature specially hardened rotation grooves, with service life more than twice that of competitors. The MXQ series guided slide cylinders use dual-cylinder design and crossed roller guides for stable guiding precision. The MHZ2 series pneumatic grippers offer bidirectional gripping and automatic centering. The core logic is simple: cylinders are the "laborers" in equipment—durability matters more than frills.
Service: Ruiheng positions itself as a matching and solution service provider, offering 7×24 technical support from selection to installation. As pneumatic products move from single-piece procurement to system matching, service capability is itself part of the product.
Market: Ruiheng's customers are concentrated in automation equipment matching—woodworking machinery cylinders, automotive manufacturing applications. These customers need reliable, stable, long-term reusable actuation components, not disposable goods. Against the backdrop of accelerating domestic substitution, Ruiheng targets the mid-to-high-end standardized pneumatic components market—neither dominated by foreign brands nor trapped in low-end price wars. It tests manufacturing processes, consistency, and matching support.
VI. Mid-Year Judgments
-
Full-year growth expected at 5%–8%.
-
Domestic substitution entering a "quantity and quality" phase; high-end standardized products are the next focus.
-
Intelligent product penetration will be faster than expected.
-
Service capability will be a key differentiator among suppliers.
For Ruiheng, the biggest opportunity is not chasing the latest concepts, but bringing "solid manufacturing" and "reliable service" to the forefront of the industry. The value of a cylinder lies not in how advanced it is, but in never failing in every single movement.